
Part two of what acquirers are really asking. First it was your AI architecture. Now it’s your people.
There’s a line in your acquirer’s model that doesn’t appear anywhere in yours. They call it headcount conversion — the projected cost and timeline of replacing your full-time staff with agentic workflows.
If you walk into a diligence call unable to answer it, the buyer won’t pause the deal to wait for you. They’ll fill the blank with their worst-case number and price you against it.
A few weeks ago, I wrote that your acquirer was already asking about your AI architecture — whether your systems could even host the automation a buyer wants to install after close. That was question one. This is question two, and it lands closer to home, because this one is about the people on your payroll.
Why the question got urgent
In February 2026, Microsoft AI chief Mustafa Suleyman told the Financial Times that AI would reach human-level performance on most professional tasks inside twelve to eighteen months. He named the jobs without flinching: lawyers, accountants, project managers, marketers. Any office work done at a keyboard. In other words-the same roles that sit inside the SG&A line a buyer reads first.
It is worth noting that Suleyman subsequently walked back that statement in June 2026, clarifying on The Verge’s Decoder podcast that he was referring to specific sub-tasks-drafting an email, building a slide deck-rather than the wholesale replacement of entire professional roles. This distinction does matter for interpreting the headline. But the market’s reaction to the original statement was real regardless of the clarification, and the underlying trend it described has not reversed.
Deal rooms did not wait for the forecast to age. Through early March 2026, tech companies had announced roughly 45,000 layoffs, and research firm RationalFX attributed approximately 9,200 of them — about one in five — directly to AI and automation based on companies’ own disclosures. By the time Q1 closed, the cumulative tech-sector total tracked by Nikkei Asia had reached 78,557, with roughly 48% of those cuts explicitly attributed to AI or workflow automation.
It’s worth noting that these attribution figures reflect what companies say, not necessarily what economists can independently verify as cause — a distinction addressed further below. Challenger, Gray & Christmas found AI was the leading stated reason for job cuts in March 2026 and again in April, though for the full first quarter, market conditions and restructuring ranked higher year-to-date.
Jack Dorsey gave it a face. In late February, Block eliminated over 4,000 jobs, or around 40% of its global workforce, and named the cause plainly: AI tools now enable smaller teams to do more. The layoff was among the largest to cite AI as a primary driver. However, some analysts noted that Block had also significantly over-hired between 2019 and 2022 and that the cuts may have partly reflected pandemic-era correction — context that complicates a clean AI-displacement reading. Snap’s Evan Spiegel followed in mid-April, announcing roughly 1,000 layoffs representing 16% of full-time staff, citing AI’s capacity to reduce repetitive work. Snap, too, had undergone layoff cycles in prior years and faced pressure from an activist investor, so the AI framing may not be the complete picture.
The pattern, however, is real: companies are telling their investors and employees that AI is enabling them to operate with fewer people. And so, your buyer is building that logic into the model they’re running on your business.
What changed inside the deal room
Two years ago, a target’s AI maturity was a checklist item. The investment thesis didn’t depend on it. That era is over.
As one private-equity finance lead framed it recently, firms are now buying the future state of the business, not the current one. Deal teams underwrite AI-enabled scale and a leaner cost structure from day one. The question flipped from “do they use AI?” to “how fast can we get them there, and what’s standing in the way?”
Your enterprise value now rides on that answer, and the math is asymmetric. Imagine two companies with identical EBITDA today. The first can show precisely which roles convert to agents, on what timeline, at what one-time cost. The buyer drops those savings straight into the operating model, raises the future-state margin, and pays for it-confidently, because the path is documented and the risk is small. The second company can’t say. So the buyer assumes it will have to run the conversion itself after close, prices in the cost, the execution risk, and the months of disruption, and takes all of it out of your number.
The asymmetry is the entire game. A missing answer costs you more than a good answer earns you, because buyers price uncertainty conservatively by trade and by temperament. That’s the nature of the game. And a vague answer is worse than no answer at all. “We’re exploring AI” tells a buyer you already know it matters and still haven’t moved — which reads as a signal about everything else they can’t see: your data quality, your systems, whether your leadership can actually execute a change of this size. That’s where the real damage hides.
None of it shows up labeled. No buyer writes “behind on AI” into a purchase agreement. It surfaces as a softer multiple, a larger holdback, a heavier earnout — a discount nobody names out loud and you can’t argue down, because it was never put on the table to argue about. The person across from you simply decided your future-state margin was a guess, then priced in that guess.
How buyers actually score your workforce now
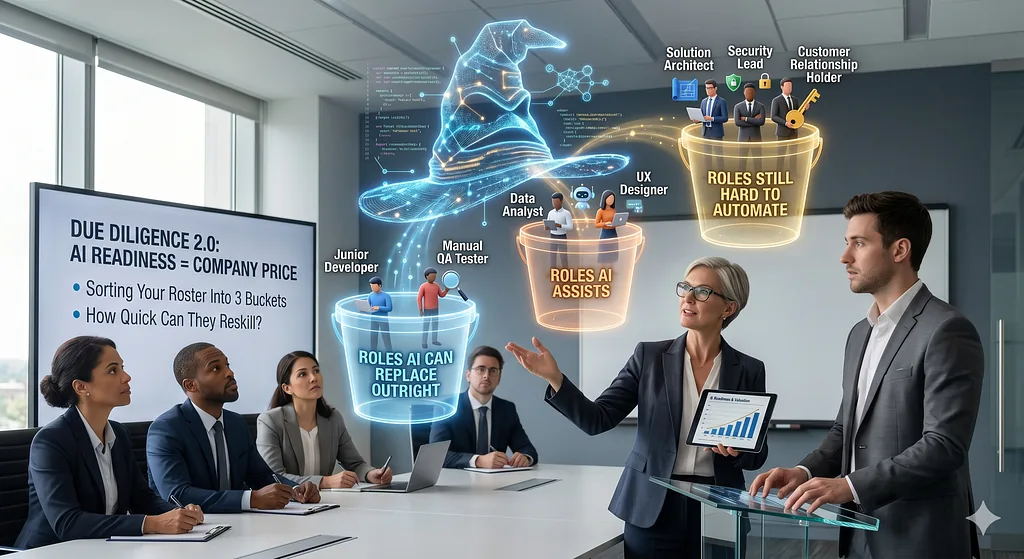
Workforce diligence used to mean checking attrition rates and flagging the key people whose departure would hurt. Now it sorts your roster into three buckets: roles AI can replace outright, roles AI assists, and roles still hard to automate.
Junior developers and manual QA testers fall into the first bucket. Solution architects, security leads, and the people who hold the customer relationships fall into the third. The buyer has stopped counting heads. They’re asking how much of your team needs reskilling, and how quickly that can happen. AI readiness has become a direct input to the price you’ll get.
This is the part that should change how you spend the next couple of quarters. The buyer isn’t trying to learn whether you’ve heard of agents. They’re trying to learn whether you’ve done the work of mapping your own company against the automation curve-and whether the map holds up under questions. A founder who can walk a diligence team through that map, role by role, is selling a future state the buyer can underwrite. A founder who improvises is selling a question mark, and question marks trade at a discount.
The mistake that looks like progress
Here’s where many founders get it wrong, and where you can get it right. The credible plan is not a bloodbath.
A Gartner survey of 350 global business executives at companies with at least $1 billion in annual revenue — all of them already piloting or deploying AI agents, autonomous technologies, or digital twins — found that 80% had reduced headcount. Some by as much as 20% of their workforce. The data was collected in Q3 2025 and published in May 2026. Bear in mind that the finding applies specifically to this self-selected population of active AI deployers, not to the broader corporate universe. Among that group, however, the result was unambiguous: companies that cut the deepest posted virtually the same financial returns as those that cut the least. In fact, several of the lighter cutters did better.
Gartner’s lead analyst on the research drew the line as cleanly as it can be drawn: layoffs create budget room, not return. Those are different things, but most boards are treating them as if they were the same.
The firms posting real gains used AI to make people more productive, not to delete them. The finding has a hard edge to it: cut too deep and you lose the institutional knowledge that makes the automation work at all. The team that knows why the customer churns, where the data is buried, and which process actually breaks under load — that knowledge doesn’t transfer to an agent on the day you escort its owner out of the building.
So the transition plan rewarded by a sophisticated buyer is surgical, not bloody. It pairs margin expansion with retained capability. It names who you keep and why their judgment makes the automation pay off rather than fail quietly. The founders who protect their valuation aren’t the ones who’ve gutted their teams to look lean on a slide, and they aren’t the ones who’ve done nothing. They’re the narrow middle-the ones holding an evidence-based conversion model and the judgment to know which cuts would cost more than they save.
This is worth saying plainly, because your buyer is skeptical and they’re right to be: the honest reading of the data is genuinely mixed. A Duke and NBER survey of 750 CFOs found fewer than half plan any AI-related job cuts this year, amounting to roughly 0.4% of the total workforce. Goldman Sachs economists found no meaningful link between AI adoption and productivity at the economy-wide level just yet, identifying gains only in two narrow use cases — coding and customer service.
Dario Amodei, who spent much of 2025 warning that AI could eliminate half of entry-level white-collar roles, reversed course in May 2026, suggesting automation may expand rather than eliminate professional work. The displacement is real and accelerating. The proven return, at scale, is not yet here. A buyer who understands both facts will reward the founder who understands both just as well — and will discount the one selling either hype or denial.
If you sell by the seat, it cuts at you twice
The conversion threatens your revenue from the other direction as well.
Stanford’s 2026 AI Index shows employment among software developers aged 22–25 has fallen nearly 20% since 2024, even as headcount for older developers has held steady or grown. The same pattern is appearing in customer support roles.
These are exactly the seats that drive expansion inside per-seat software contracts. A 20% reduction in junior headcount at your largest customer isn’t routine churn. It’s a structural shrink in the user base your ARR is built on. Your buyer is modeling that contraction against your renewal assumptions while you’re still modeling growth. Close that gap before they do it for you in a diligence memo.
Build the answer before someone builds it for you
Five things belong in your data room before the LOI lands:
• A workforce map. Every role sorted into replaceable, assist, or hard-to-automate, with current fully-loaded cost attached to each bucket. This is the document the buyer is otherwise guessing at.
• A conversion roadmap. Timeline, one-time cost to convert, and the steady-state cost structure you’re driving toward. Give the buyer the math so they don’t invent their own.
• Proof you’ve started. Named pilots with real results, not intentions. Specificity is what turns a worst-case assumption into a number a buyer will actually underwrite.
• A retention story. Who you keep, and why their judgment makes the automation pay off. This is your answer to the Gartner problem, and it signals operational maturity better than any cut.
• A revenue-durability cut, for SaaS. Evidence that your ARR doesn’t rest on seats about to disappear from your customers’ org charts.
The third question is coming
The first question was whether your architecture could host the future. The second is whether your workforce can become it. There’s a third on the way — the one about capital, about whether the savings actually fund growth or just free up room on a slide while returns stay flat. I’ll get to that.
But for now, the move is simple. Your acquirer’s model already has the headcount-conversion line filled in. The only open question is whether the number being used is yours or theirs. In most companies right now, it’s theirs. Change that before the LOI arrives, because once the deal is on the table, the discount is already baked into the price, and nobody in the room will tell you it’s there.
References
Challenger, Gray & Christmas. (2026, April 2). Challenger report: March cuts rise 25% from February, AI leads reasons. https://www.challengergray.com/blog/challenger-report-march-cuts-rise-25-from-february-ai-leads-reasons/
Challenger, Gray & Christmas. (2026, May). Challenger report: April job cuts rise 38% from March; YTD cuts down 50%. https://www.challengergray.com/blog/challenger-report-april-job-cuts-rise-38-from-march-ytd-cuts-down-50/
CryptoBriefing. (2026, June 9). Microsoft AI chief clarifies automation comments, walks back job replacement timeline. https://cryptobriefing.com/microsoft-suleyman-clarifies-ai-automation-comments/
Fortune. (2026, March 24). CFO survey: AI job cuts productivity paradox 2026. https://fortune.com/2026/03/24/cfo-survey-ai-job-cuts-productivity-paradox-2026
Fortune. (2026, May 5). Dario Amodei spent last year warning of an AI white-collar bloodbath. Now he’s changing the narrative. https://fortune.com/2026/05/05/dario-amodei-jevons-paradox-will-ai-wipe-out-white-collar-jobs/
Fortune. (2026, May 11). AI isn’t paying off in the way companies think. Layoffs driven by automation are failing to generate returns, study finds. https://fortune.com/2026/05/11/ai-automation-layoffs-gartner-study-roi/
Fortune. (2026, May 26). Sam Altman and Dario Amodei are both walking back their AI jobs apocalypse prophecies as they eye blockbuster IPOs. https://fortune.com/2026/05/26/sam-altman-dario-amodei-walking-back-ai-jobs-apocalypse-prophecies-ipo/
Gartner. (2026, May 5). Gartner says autonomous business and AI layoffs may create budget room, but do not deliver returns. https://www.gartner.com/en/newsroom/press-releases/2026-05-05-gartner-says-autonomous-business-and-artificial-intelligence-layoffs-may-create-budget-room-but-do-not-deliver-returns
IBTimes UK. (2026, March 25). Tech layoffs surge to 59,000 in 2026 as Amazon, Meta and Block cut jobs amid AI shift. https://www.ibtimes.co.uk/ai-driven-layoffs-2026-tech-sector-1788111
Bersin, J. (2026, March 2). Is Block’s decision to layoff 40% of its workforce a bellwether or not? https://joshbersin.com/2026/03/is-blocks-decision-to-layoff-40-of-its-workforce-a-bellwether-or-not/
Metaintro. (2026, March 13). The AI productivity puzzle: Why 80% of companies report zero productivity gains from AI. https://www.metaintro.com/blog/ai-productivity-paradox-2026-companies-no-gains-economists-breakthrough
Stanford Human-Centered AI Institute. (2026). Inside the AI Index: 12 takeaways from the 2026 report. https://hai.stanford.edu/news/inside-the-ai-index-12-takeaways-from-the-2026-report
The AI Consulting Network. (2026, April 26). 78K Q1 tech layoffs: What AI cuts mean for CRE in 2026. https://www.theaiconsultingnetwork.com/blog/q1-2026-tech-layoffs-78000-ai-cre-office-investors
Yahoo Finance / AfroTech. (2026, May). Microsoft AI CEO has a prediction for the future of white-collar work over the next 18 months. https://finance.yahoo.com/sectors/technology/articles/microsoft-ai-ceo-prediction-future-154055391.html
Fast Company. (2026, April 15). Snap layoffs today: 16% of jobs cut as CEO Evan Spiegel is the latest to tout AI advances. https://www.fastcompany.com/91527233/snap-snapchat-layoffs-today-job-cuts-as-ceo-evan-spiegel-touts-ai-advances
AOL / Business Insider. (2026, February). Jack Dorsey just laid off 40% of staff. He said he’s still hiring AI engineers. https://www.aol.com/news/jack-dorsey-just-laid-off-013103692.html
AOL Finance. (2026). Goldman finds “no meaningful relationship between AI and productivity at the economy-wide level.” https://www.aol.com/finance/goldman-finds-no-meaningful-relationship-143553240.html
By Ivan Ruzic, Ph.D. · Originally published on Medium